European health companies to watch in 2026
The companies behind Europe’s $703B health sector: 46 young companies to watch and the 57 European companies on Dealroom’s hottest AI healthtech map, then the largest by value and the nine bought for $1.5B or more since 2024.
 By Yoram Wijngaarde and Dealroom API ·
Companies to watch
The map below combines two lists, 81 companies in all. 46 are young companies founded since 2018, picked from the 400 European health companies that score highest on Dealroom Signal, a rating of a company’s growth, team and timing. 57 are the European companies on Dealroom’s hottest AI healthtech companies map, which lists the 203 private AI health companies with the highest Signal worldwide; 123 of those are in the United States. 22 companies are on both lists. The 12 marked 🔥 score highest while still early, with $50M or less raised. A separate landscape of AI in health in Europe covers the wider field.
81 European health companies to watch
Young companies picked with Dealroom Signal and the European companies on the hottest AI healthtech map, by subsector
What is emerging
Comparing the 21 months to September 2026 with the 21 months before shows which parts of healthtech are pulling in more money. Sleep tech, health wearables, longevity and preventive care grew fastest, though in each of them one company raised much of the money. Growth is broader in AI drug discovery, which raised $5.3B across 209 rounds, and in immune and inflammatory disease. AI tools that write up clinicians’ notes are behind the growth in AI assistants. Digital therapeutics, medical testing, mental health, and women’s health and fertility raised less than two years earlier.
Sleep, wearables, longevity and preventive care grew three- to eightfold in the last 21 months
Health subsectors: venture capital raised against growth
AI in healthtech
Companies Dealroom tags as building with AI took 48% of the venture capital raised by European health companies between January and September 2026, up from 22% in 2025 and 11% in 2015. One $2.1B round is part of that; without it the share is 35%, still above the 32% of US health venture capital that went to AI companies over the same months.
AI companies took 45% of European biotech and pharma venture capital in 2026 so far, up from 20% in 2025
Share of European venture capital raised by companies tagged AI
The largest companies
Biotech and pharma companies make up $566B of the $703B that Europe’s venture-backed health companies are worth. Listed drug developers such as argenx and Genmab are the largest single companies; most of the value sits with hundreds of smaller ones. Among private companies the most valuable are ŌURA ($10.9B), Isomorphic Labs ($8.4B), Neko Health ($7.0B), Doctolib ($3.9B) and CMR Surgical ($3.0B).
Biotech and pharma companies make up $566B of the $703B
Latest valuation by segment and company, listed, private and acquired; each company counted once
 argenx$54.7B · ListedNetherlands
 Horizon$27.8B · AcquiredIreland
 Genmab$25.4B · ListedDenmark
 Verona$10.0BUK
 Isomorphic$8.4BUK
 BioNTech$8.2BGermany
 Alvotech$3.4BIceland
 Tubulis$3.2BGermany
 ATAI Life Sciences$2.8BGermany
 MorphoSys$2.7BGermany
 Polyplus-transfection$2.6BFrance
 UniQure$2.2BNetherlands
 Synthon$2.2BNetherlands
 Oxford Nanopore$2.1BUK
 Neko$7.0BSweden
 CMR Surgical$3.0BUK
 Doctolib$3.9BFrance
 Kry$2.0BSweden
The ones that were bought
Large acquisitions have become more frequent. Since 2023, 22 venture-backed European health companies have been bought for $1B or more, against 13 from 2015 to 2022. Since 2024, nine have been bought by drug or medtech companies for $1.5B or more. The largest was Merck & Co’s $10.0B purchase of Verona Pharma, which makes an inhaled treatment for chronic lung disease. Four of the nine started as spinouts from universities or research institutes. Six of the buyers are from outside Europe: four from the United States, one from Australia and one from Japan.
22 European health companies have been bought for $1B or more since 2023, against 13 in the eight years before
Acquisitions of $1B or more of venture-backed European health companies, by year; 2026 is January to September
Nine European health companies have been bought for $1.5B or more since 2024, for $34.7B in total
Acquisitions by drug and medtech companies since January 2024, by price paid


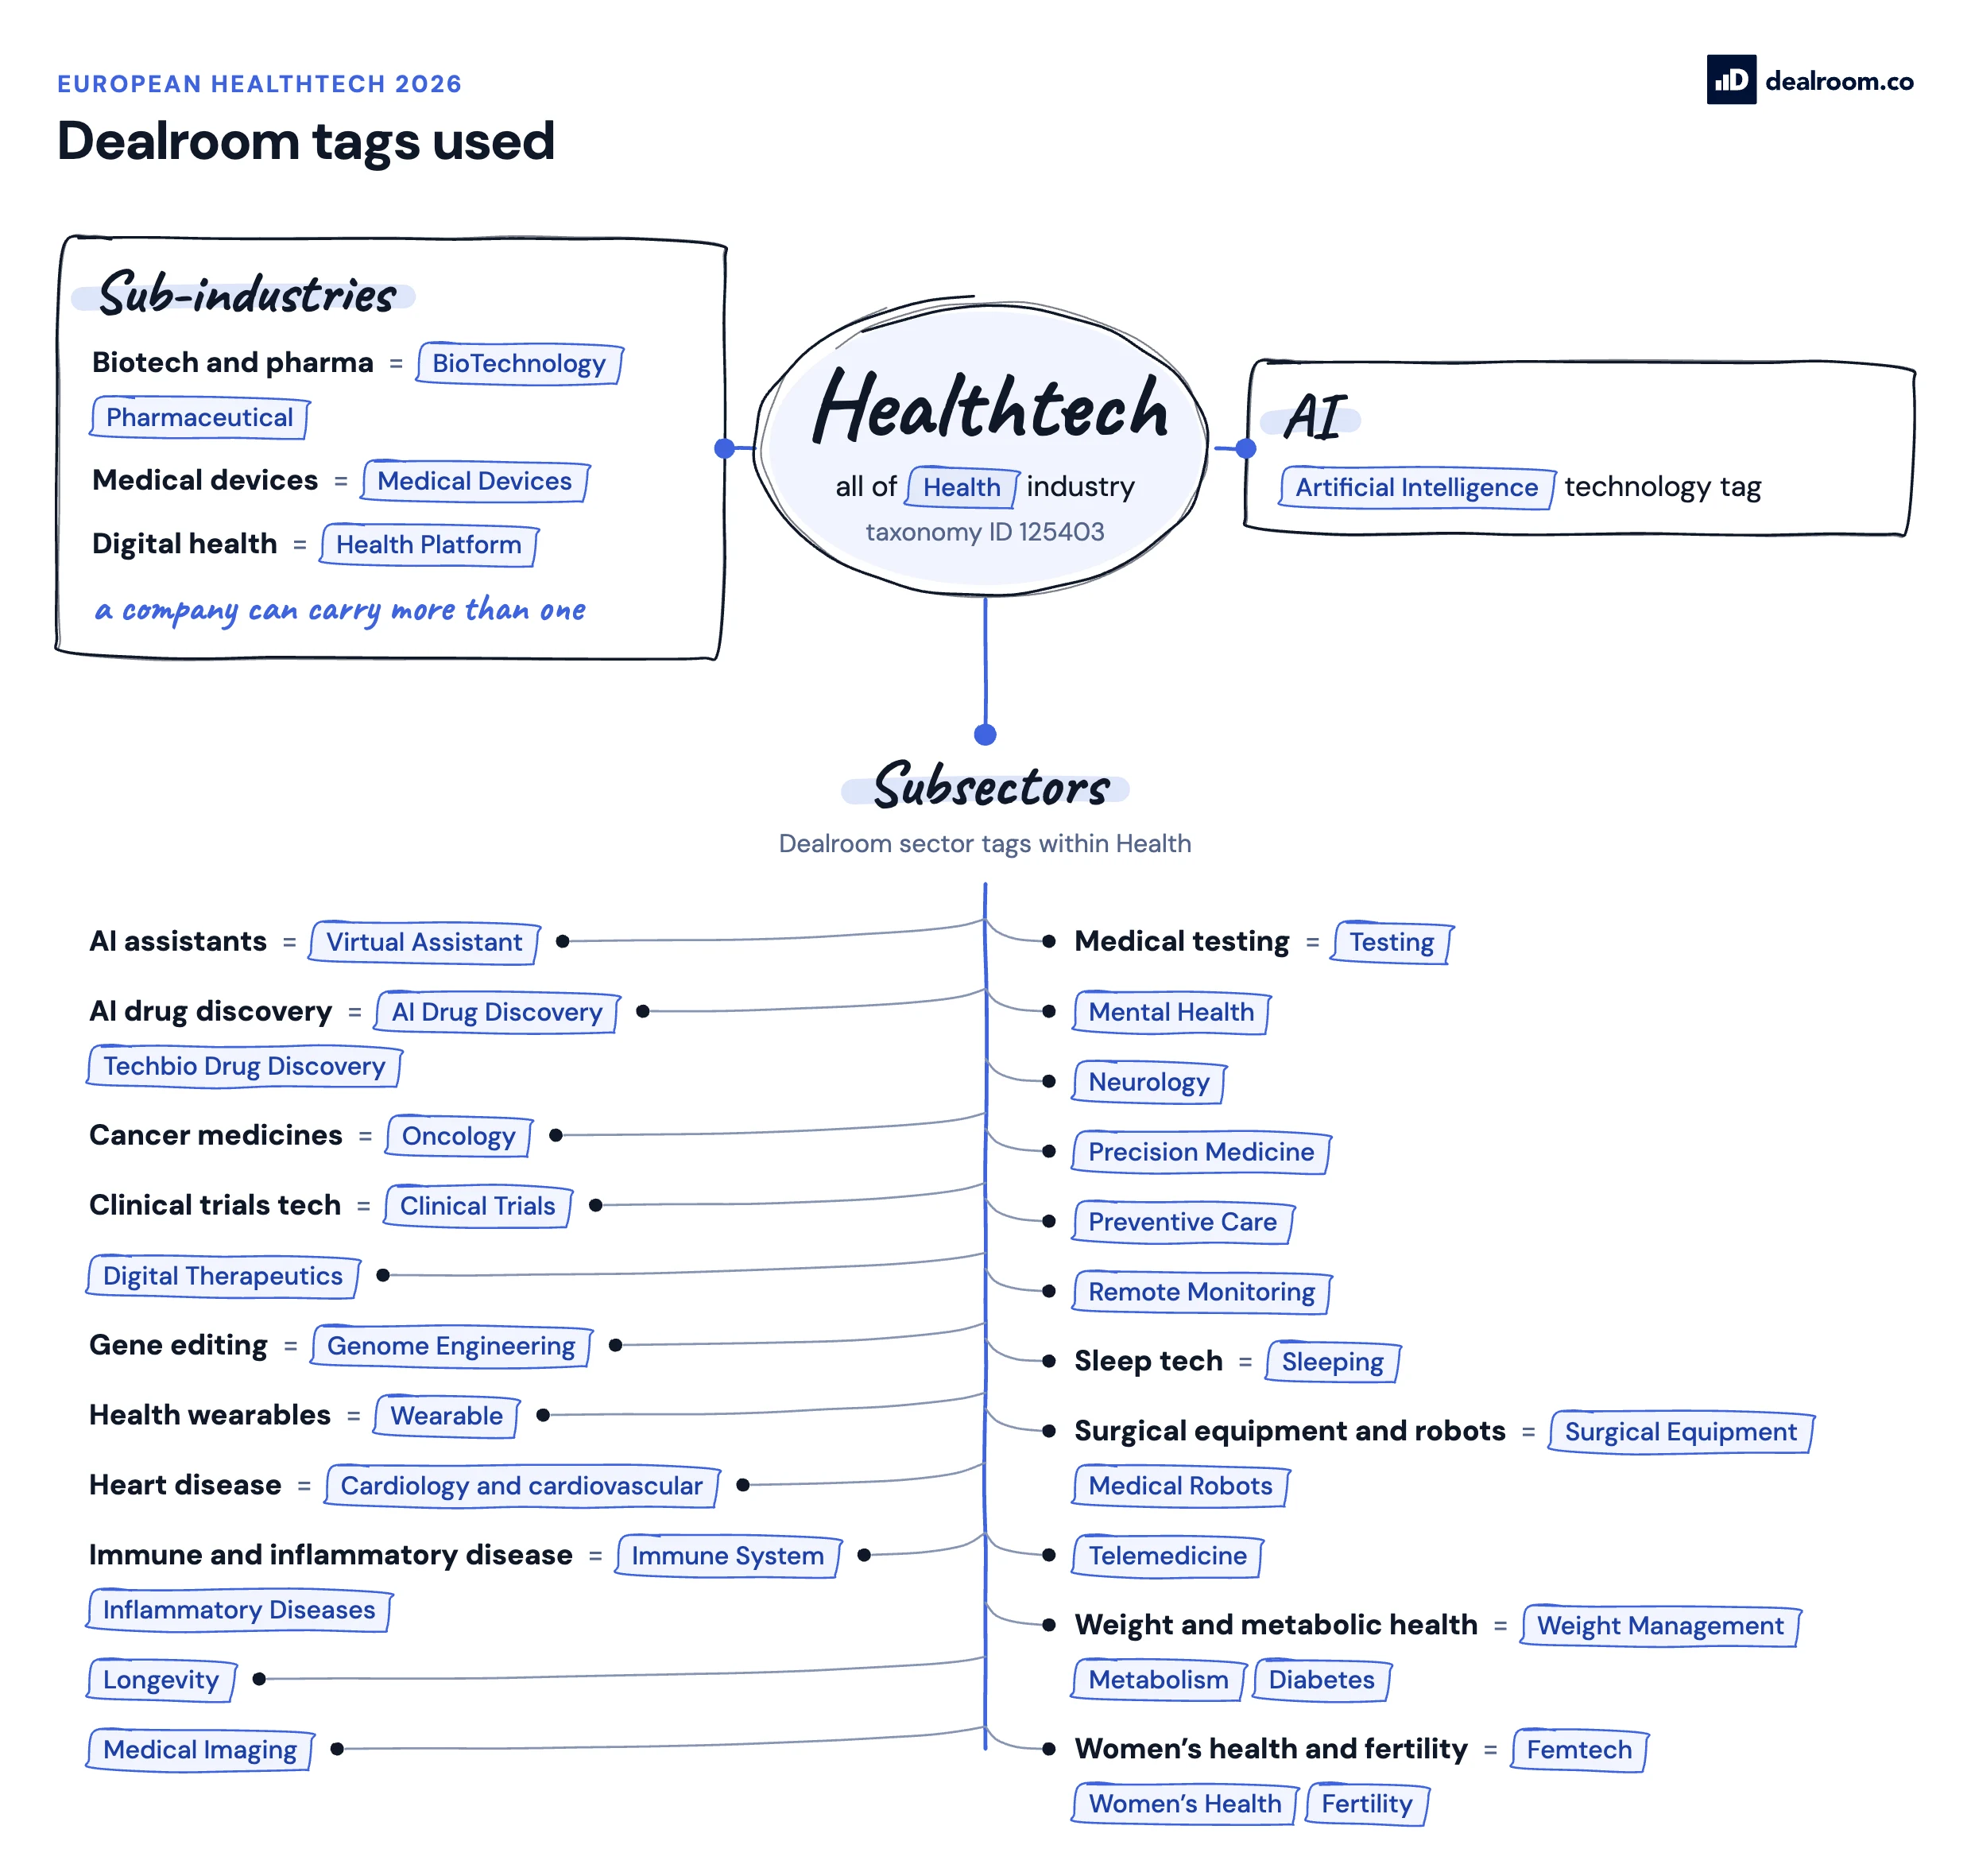
Dealroom tags used, as a list
- Healthtech: every company in Dealroom’s Health industry (taxonomy ID 125403).
- Biotech and pharma: the BioTechnology and Pharmaceutical sub-industries. Medical devices: Medical Devices. Digital health: Health Platform. A company can carry more than one.
- Subsectors: Dealroom sector tags within Health. AI assistants = Virtual Assistant; AI drug discovery = AI Drug Discovery, Techbio Drug Discovery; Cancer medicines = Oncology; Clinical trials tech = Clinical Trials; Digital therapeutics = Digital Therapeutics; Gene editing = Genome Engineering; Health wearables = Wearable; Heart disease = Cardiology and cardiovascular; Immune and inflammatory disease = Immune System, Inflammatory Diseases; Longevity = Longevity; Medical imaging = Medical Imaging; Medical testing = Testing; Mental health = Mental Health; Neurology = Neurology; Precision medicine = Precision Medicine; Preventive care = Preventive Care; Remote monitoring = Remote Monitoring; Sleep tech = Sleeping; Surgical equipment and robots = Surgical Equipment, Medical Robots; Telemedicine = Telemedicine; Weight and metabolic health = Weight Management, Metabolism, Diabetes; Women’s health and fertility = Femtech, Women’s Health, Fertility.
- AI: the Artificial Intelligence technology tag.
- Venture capital: rounds Dealroom marks as venture rounds, raised by venture-backed companies, in US dollars, counted where the company is headquartered.
- Europe: Dealroom’s Europe location (the continent, including the UK and Switzerland). United States: the country.
- Value: the latest valuation of venture-backed health companies founded since 1990 that have not closed. Public = the Public ownership tag; Acquired = company status acquired; Private = the rest.
- Signal: Dealroom’s score for a company’s growth, team and timing. 🔥 = Signal 92 or higher (or the three highest at 85+), $50M or less raised, not a unicorn, not exited.
- Acquisitions: exits of $1.5B or more since January 2024, bought by drug or medtech companies.
Data and method
Source: Dealroom, retrieved 2026-10-06, USD. Healthtech is Dealroom’s Health industry (taxonomy 125403), which includes the sub-industries BioTechnology, Pharmaceutical, Medical Devices and Health Platform (digital health). Europe is the Europe continent location. Venture capital is rounds flagged as venture rounds, for venture-backed companies, by company headquarters. Value is the sum of the latest valuations of venture-backed health companies founded since 1990 and not closed, including listed companies at market value; the 2026 bar is the latest. 2026 covers January to September, compared with the same months of 2025; rounds carry month precision. The 2026 annual pace scales January to September by twelve ninths; it is an estimate, not a forecast. Subsectors are Dealroom sector tags inside Health, chosen from every tag with $250M or more in January 2025 to September 2026, leaving out programme, list and country tags, with overlapping tags merged; they are compared with January 2023 to September 2024. AI is Dealroom’s Artificial Intelligence technology tag. Round-size bands count 2021–2025 rounds with a disclosed amount. The United States uses the same rules with the US country location. Country figures use company headquarters; per-person figures divide the 2021–2025 yearly average by population from Dealroom location data. The value treemap puts each company in one segment, in the order biotech and pharma, medical devices, digital health, other, so segments add up to the total; companies too small to label are unnamed blocks, counted in “Other”, and the finely gridded block is every company below the largest 600 in its segment. Acquisitions are exits of $1.5B or more since January 2024 bought by drug or medtech companies; the buyer is taken from the source Dealroom records on each deal. Synthon, sold for about $2.2B in December 2024 to Goldman Sachs Alternatives, a private-equity buyer, is excluded. AtaiBeckley is recorded on Dealroom as ATAI Life Sciences. Spinouts follow Dealroom’s spinout flag. The companies to watch were picked from the 400 operational, venture-backed European health companies founded since 2018 with the highest Dealroom Signal, leaving out companies outside human health and those without disclosed funding. 🔥 marks companies with Signal 92 or higher (or the three highest at 85 or higher) that have raised $50M or less, are not unicorns and have not exited. The map adds the European companies on the hottest AI healthtech map; one that is not on the watch list sits in the subsector closest to its segment on that map.